

Direct Investors or an SPV? How Crowdfunding Changes Your Cap Table
After an equity crowdfunding raise, you have new owners to keep track of, communicate with and, in some cases, involve in company votes. How you organize that ownership affects the work ahead. Your list of who owns what is called a cap table, and there are two ways to put crowd investors on it.
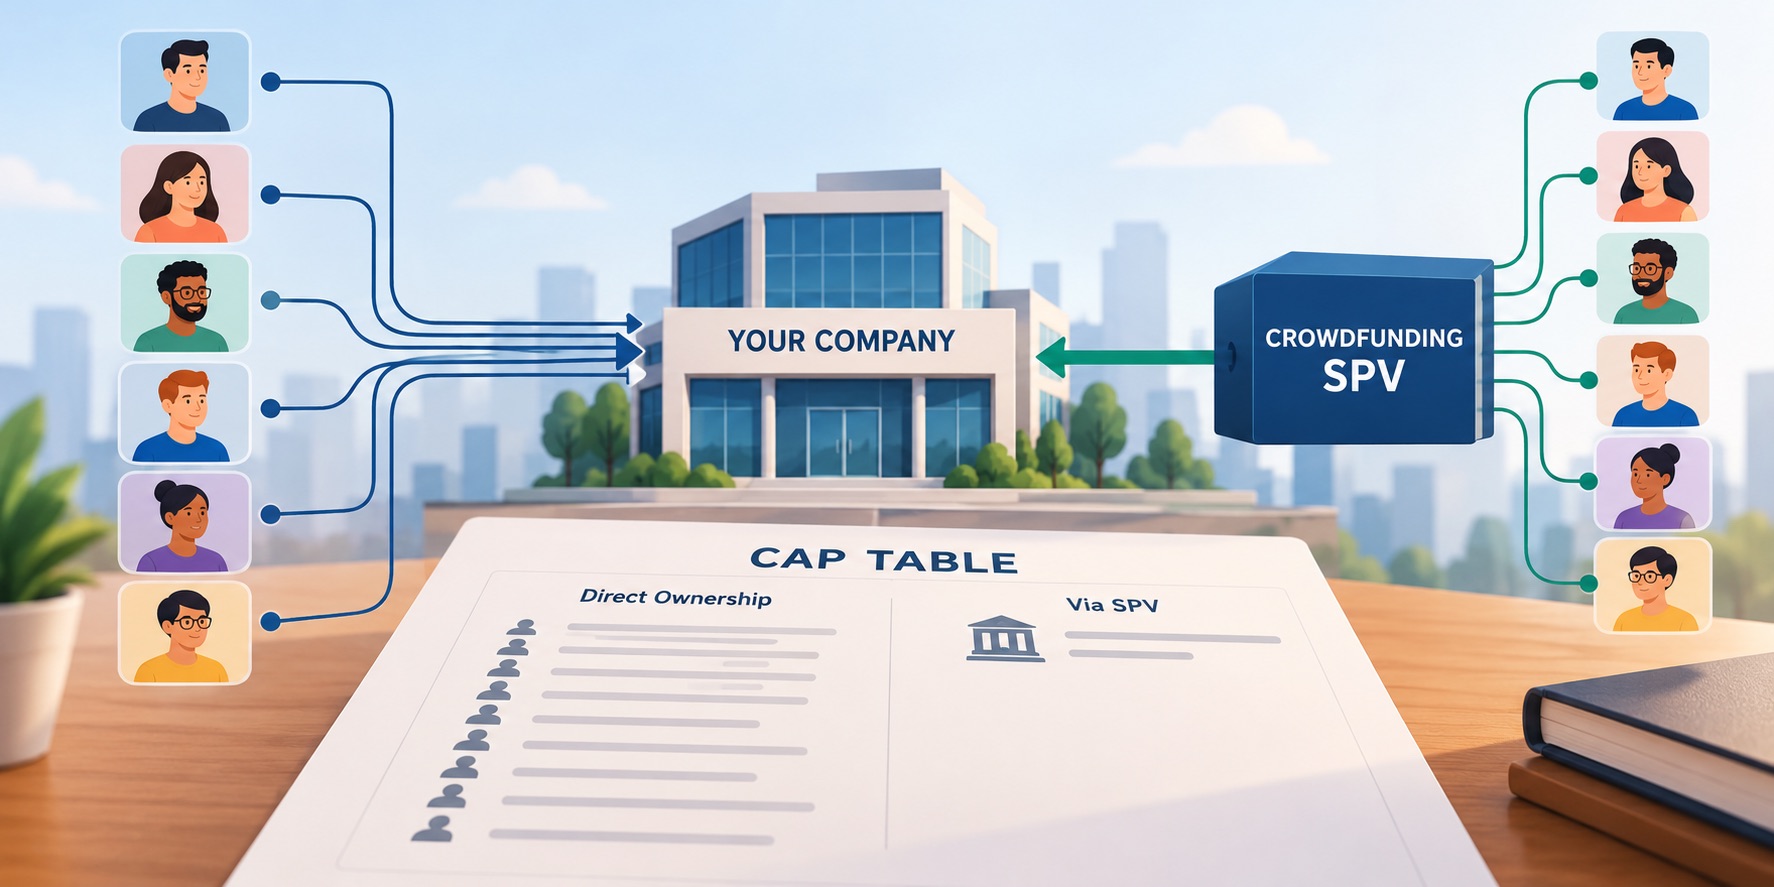
This comparison uses shares to explain the difference. With direct ownership, each investor owns shares in your company and appears individually in its ownership records. The group option uses a separate company set up only to hold your investors' shares, called a crowdfunding SPV (special purpose vehicle). The vehicle owns the company shares, and each investor owns a matching piece of the vehicle, which may be able to appear as one entry on your cap table.
Direct ownership avoids that extra company, but each investor remains a separate shareholder whose ownership and rights must be administered. Although, a registered transfer agent can handle much of the recordkeeping that comes with a large shareholder base.
What is a cap table, and why does it matter after crowdfunding?
Think of the cap table as your ownership map: it shows who holds shares in the business and how many each holds. Every owner brings work, including keeping ownership records, sending required information and organizing any votes.
The length of that list can also matter when planning another raise. In the discussion leading to the vehicle rules, some commenters raised concerns about messy ownership records. The SEC also described a concern that a long, unwieldy cap table could discourage founders hoping to raise from larger investors later from using crowdfunding. That is a concern about future fundraising, not evidence that direct ownership puts later investors off.
Keeping investors direct avoids the work and costs of running another company. A vehicle offers a way to organize the crowd separately, with costs of its own. Your expected investor numbers, those costs and your future fundraising plans all feed into the comparison.
This article focuses on Regulation Crowdfunding (Reg CF), which allows companies to raise money from the public online through a registered intermediary, the service through which the raise takes place. For the broader basics, see What Is Equity Crowdfunding?.
What would direct ownership and a crowdfunding SPV look like?
For Reg CF, the specific structure is called a crowdfunding vehicle. Only an SPV that meets the conditions in the SEC's Rule 3a-9 can be used this way, including that it exists only to hold investments in one company.
Here's a made-up example using shares. Say 800 people each invest $500, buying 100 shares at $5 each. Together, they invest $400,000 for 80,000 shares. These numbers are only for illustration:
- Direct ownership: Each of the 800 investors holds 100 company shares and is listed individually in the company's ownership records, giving you 800 investor entries.
- Vehicle ownership: The vehicle holds all 80,000 company shares, and each investor owns 100 matching pieces of the vehicle. Your cap table may be able to show one entry for the vehicle, with all 800 investors holding their investment through it.
“Matching” matters here. For every company share the vehicle holds, its investors own one matching piece with the same terms and rights. The vehicle's money goes into that one company's investments, and it has no freedom to pick other companies to invest in.
Why consider direct investors, and why consider a vehicle?
Direct ownership keeps the relationship between the company and its shareholders direct. There is no extra holding company to create, run or eventually close, so the company avoids the costs that come with one.
Each investor still has to be maintained as a separate shareholder, but that does not necessarily mean the founders manage hundreds of names themselves. Companies can use a registered transfer agent to maintain security-holder records and process ownership changes. The practical question is therefore not just how many investors you have, but who will administer them and what that service will cost.
A vehicle offers a different way to organize that work. It can handle the records and communications itself or hire another provider to do so, including contacting investors about votes. That changes who runs those tasks.
Your company must fund or reimburse the vehicle's setup, operating and closing expenses, and if anyone is paid to operate the vehicle, that pay must come from the company. The costs cover the vehicle's life, from setting it up through running it and eventually closing it.
What changes for investors' votes, information and rights?
For investors, a vehicle adds a step between them and your company. The rules are designed so that, even with that step, they keep the same financial terms, voting power and required information they'd have as direct shareholders.
Some shares come with votes and others don't; the offering document must explain those rights and any limits. If the company's shares carry votes, the vehicle must ask its investors how to vote and follow their instructions. Whoever runs it must take that step before casting the votes.
The vehicle must promptly pass along the information required under Reg CF. It must also give investors any information it receives from the company as a shareholder.
Investors can also tell the vehicle to act on their behalf to enforce the legal rights they'd have as direct shareholders. Small legal differences can remain because investors own a piece of the vehicle, with the vehicle holding the company shares.
Does one cap-table entry mean less reporting?
After selling investments under Reg CF, the company must file annual reports with the SEC and post them on its website until it meets a condition that allows reporting to stop.
One stopping condition depends on the number of investors. For that purpose, SEC staff guidance dated July 9, 2026 says the people who invested through the vehicle still count individually. A group entry on the cap table therefore isn't a shortcut to ending those annual reports.
There is a separate federal shareholder-count rule under Section 12(g) of the Exchange Act. Generally, a company with more than $10 million in total assets must register a class of equity securities with the SEC if that class is held of record by 2,000 or more people, or 500 or more people who are not accredited investors. Registration brings a broader set of ongoing SEC reporting requirements.
Reg CF provides special relief from that rule. Securities sold under Reg CF generally can be excluded from the Section 12(g) holder count while the company is current on its required Reg CF annual reports, has $25 million or less in total assets at the end of its last fiscal year and uses an SEC-registered transfer agent.
So having hundreds of direct Reg CF investors does not, by itself, mean a company becomes an SEC-reporting company. The Reg CF annual-reporting rules and the Section 12(g) registration rules are separate tests.
What should you ask before choosing an ownership structure?
A securities lawyer (one who works on fundraising and investment offerings) and an accountant can help you apply this comparison to your own plans. Questions worth asking them:
- How would our expected investor numbers and future fundraising plans affect the administrative work in each structure?
- What would a vehicle cost to set up, run and close, and who would handle its records and communications?
- Who would collect voting instructions and handle any signatures our documents require?
- What differences in investors' legal rights would our proposed documents create?
For the wider preparation process, see How to Raise From the Crowd.
FAQ
Is a crowdfunding vehicle required for a Reg CF raise?
No. Using a crowdfunding vehicle is optional. A company can raise directly from investors without adding a vehicle.
Can a company offer shares directly and through a vehicle?
A company can offer shares directly and through a crowdfunding vehicle, with a separate Form C filing for each offering. Form C is the document describing the business, finances, investment terms and risks. For the vehicle offering, the company and vehicle file jointly.
Weighing the two options
A shorter ownership list still leaves people behind it who need records, information and a way to exercise their rights. Direct ownership keeps that relationship with your company. A vehicle puts another company between you and those investors, which can change who handles the work and adds expenses your business pays. Comparing that work and cost with your expected investor numbers and fundraising plans gives you a starting point for evaluating both options.
Planning ownership is one part of preparing to raise. Building an audience is another. EquityCF helps founders build a following on a free company profile before launching a raise.
Related Articles